For Australian parents of kids 3 – 12
Three Lil Banks for your little ones.
Four Lil Banks as they grow.
And Twelve lessons on why.
A pocket-money system you can install in one evening — and a free app that helps your kid run it the next morning. Built for Aussie families. Not a bank.
Free Our Money Rules · No sign-up · No trackers · Not a bank
Our Money Rules
Every Saturday, Eli receives $10.
Signed: Mum · Dad · Eli
The premise, in one sentence
Most pocket-money advice teaches kids to budget.
This one teaches them to build wealth.
Budgeting divides what you have. Wealth-building thinks upstream. Where does the money come from? How do we get some of it working while we sleep? That's the wiring worth installing — while their brain is still soft.
Why the window matters
The age by which most core money habits are set.
University of Cambridge, on habit formation. That's not a warning — it's an opportunity. From 3 to 7, your child's brain is uniquely open to the rules of money. Miss it and you're retrofitting at 30.
"You're the primary financial educator your kid is ever going to have. Not the school. Not the influencer."
— From Lesson 1
The five pillars
Earn. Save. Spend. Give. Invest.
Five concepts. Not one is optional. Together they teach a child what a lifetime of half-good money advice leaves out.
Earn
The input
Money comes from creating value for someone. Not from existing. Earn isn't a Bank — it's the concept your kid carries with them.
Save Bank
Short-term restraint
Money reserved for something specific — a Lego set, a Saturday. The dopamine of "I chose to wait and got the thing."
Spend Bank
Guilt-free consumption
Yours to spend, judgment-free. Even on rubbish. The 7-year-old who blows theirs on glow sticks is learning more than the one who was stopped.
Give Bank
Generosity as identity
Wired in early, before the "once I have enough" mindset takes hold. There's no amount that's enough. Giving is a habit, not a milestone.
Invest Bank
Money that grows
The wealth-builder's lever. Add it when your family's ready — usually 6 to 8. Compound interest at $50; you don't want to wait until $50k.
Every family starts at three Banks. The fourth opens when you're ready. It's one toggle.
The invisible pillar — Wants vs Needs
The five pillars only work
if your kid can answer one question.
Before Save or Spend or Give or Invest means anything, a kid has to sort what's in front of them into two piles: things I actually need, and things I just want right now.
The Wants vs Needs conversation is the one habit that carries them into adulthood. It's why the last screen your kid sees before they tap Spend in the app asks: "was this a want or a need?" — not to shame them, to make them notice.
It's the whole pillar behind Lesson 4. And it's the one moment your seven-year-old teaches your eleven-year-old.
Need
- •School shoes that fit
- •Lunch on Wednesday
- •A raincoat before winter
- •Birthday gift for a friend
Want
- •The third Squishmallow
- •Cinema popcorn (again)
- •Roblox Robux this week
- •The same Lego, one size up
Lil Banks · Confidential
Parent Money Audit
Ten questions. Fifteen minutes. Nobody sees this.
Lesson 2 asks the question nobody wants to ask
"You can't teach what you haven't examined."
The Parent Money Audit is ten questions about the money language you grew up with, the language you use now, and the unconscious signals your kids are already absorbing. It's fifteen minutes. Nobody sees your answers.
Included free with the Our Money Rules template below.
Lesson 10, the keystone
"Time crushes amount.
Start now, even with peanuts, and you win."
Two kids. One puts $100 in every birthday from 12 to 30. The other starts at 30 and puts in $300 a year until 62. The second kid puts in $9,600. The first puts in $1,800. Same outcome at 62. The only difference is when they started.
The penny that doubled every day
Show your kid this weekend. Watch their face at day 20. That's the moment compound interest becomes real — and the moment the whole system clicks.
Where we're different
They speak to your kid.
We speak to you.
Most of the market
- ✗Kid-direct (books, Roblox, characters)
- ✗Builds curiosity, not habit
- ✗Skips parent mindset entirely
- ✗Multi-week onboarding through an ecosystem
- ✗US-shaped, US-priced
Lil Banks
- ✓Parent-facing (you teach the kid)
- ✓One evening to read, then a habit
- ✓Module 1 is your own money audit first
- ✓One-page Our Money Rules, signed by Saturday
- ✓Made in Australia, priced for Aussie families 🇦🇺
The companion app
Free. Local-first.
No ads, no trackers, ever.
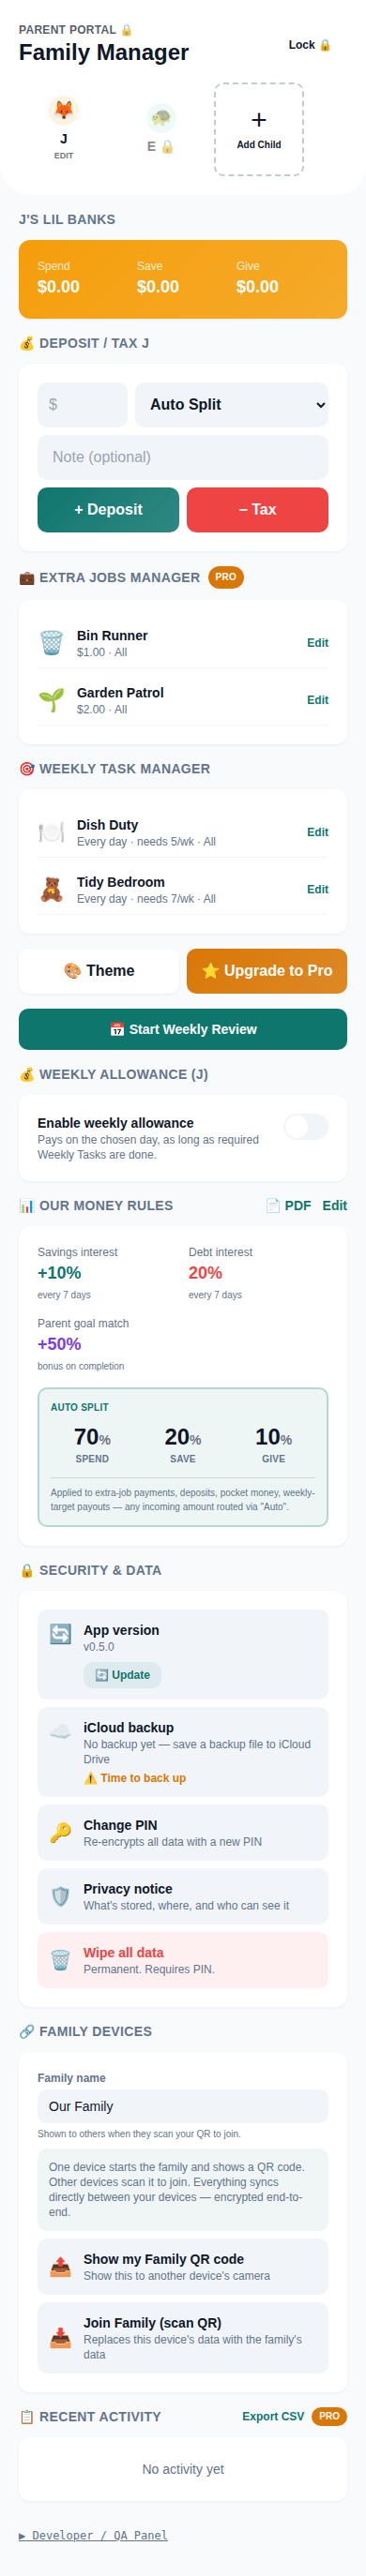
The app runs the system for you. Payday auto-pays. Splits happen automatically. Weekly Review keeps the whole family on the same page. No sign-up. No email. No account. Data lives on your device.
- ●Free forever with one child on one device. Every feature works.
- ●Installs on iPhone, iPad, Android, desktop — like a real app, from the browser.
- ●The Weekly Review runs the Saturday sit-down for you.
- ●Export Our Money Rules as a printable PDF anytime.
Simulation only. No real money moves through it — deliberately.
Start tonight
Get Our Money Rules.
Free.
A one-page printable template you and your kid fill in together. Plus the ten-question Parent Money Audit. Signed by Saturday. On the fridge by Sunday.
Ready for the full system?
Twelve lessons.
Ninety minutes total.
Written for a parent who wants the whole system by next weekend. Read in an evening. Ship the first payday on Saturday.
Module 1 — Foundations
- Why pocket money is the wrong question
- Your money story (parent audit)
- The trust foundation
Module 2 — The system
- The five pillars, three or four Banks
- When to start at each age
- How much to give
- Base + Commission (Extra Paid Jobs in the app)
Module 3 — Setup
- Your setup plan (with the app walkthrough)
- Your first four weeks
Module 4 — Wealth-building
- Compound interest, Shares, Bonds, Property, Loans
- Earning as value creation
Module 5 — Going long
- The long game
If you want to go all-in
One recommendation.
The Family Bundle
one-time · save $19 vs buying separately
The full 12-lesson program + App Premium (year 1). Multi-child + multi-device sync included. This is how most families start.
- ✓All 12 lessons (PDF + read online)
- ✓Fillable workbook (Our Money Rules, tracker, audit)
- ✓App Premium for year 1 — multi-child, multi-device sync
- ✓Lifetime program updates
- ✓30-day refund, no questions
Just the 12-lesson program? Core — $39
Compare all tiers
App Premium
$29/yr or $99 lifetime · multi-child + multi-device sync
Everything You Wish
$49 · the adult money course for parents · see MoneyRules →
APRA confirmed in writing what we already knew. Not a bank. No customer funds held. No trackers. No ads. No collection of children's data. Ever. (June 2026.)
Who's writing this
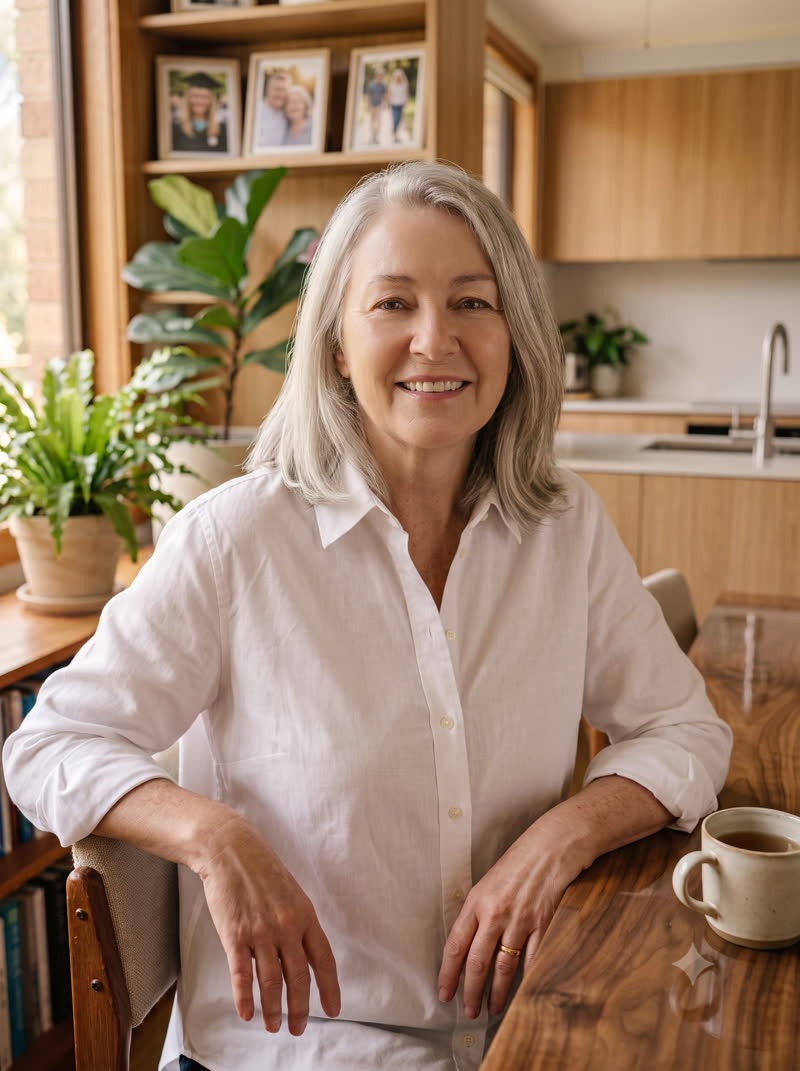
I'm Bec. Melbourne. Early retired, three grown-up kids — two of them work in finance, one runs the online business that's building this out with me.
My parents ran a pocket-money system with my brother and me from before I could count. It wasn't a course. It was just what our family did. They weren't big earners, just deliberate — and it let them retire earlier than most of their friends and be around while we were growing up. I got a childhood with my parents in it.
When I had my own three, I ran the same system. They're grown adults now, all three actively building their own wealth — which is the only reason I feel comfortable putting the system in front of your family. If it had holes, my finance kids would have called me out inside a decade.
I'm not a financial planner. Not a doctor. Not a PhD. Just a parent who inherited a system, ran it with her own kids for twenty years, and watched the research catch up to what my family had been quietly doing all along — Cambridge on habit formation, ASIC's Australian data, Kahneman on delayed gratification. Same conclusions, three generations apart. Time to write it down.
— Bec, from Lil Banks
Why we bother
Every Australian kid deserves the head start I got — the run-up of practising money as a system for ten years before they meet the real financial world. That's the whole reason Lil Banks exists.
For the parent who's here for their kid
— and wondering about themselves
Everything you wish your parents
had taught you about money.
Most pocket-money advice assumes you have money figured out yourself. This one doesn't. A separate adult course, under the Lil Banks house, for the version of the talk you should've had at 18.
Super. Compound interest. ETFs. Property. Good debt vs bad debt. Tax. With country-specific advanced modules for AU, US, UK, CA and NZ retirement systems.
Frequently asked
Straight answers.
Is Lil Banks a bank? +
No. Lil Banks is an educational publisher and software developer. It's not an Authorised Deposit-taking Institution and doesn't provide financial product advice. APRA confirmed in June 2026 that s66 of the Banking Act 1959 doesn't apply — because the business isn't financial. The app is a simulation. No real money moves.
Do you collect my kid's data? +
No. The app is local-first — everything your family enters stays on your device. No accounts, no email, no phone number. No analytics, no advertising, no telemetry. We don't monetise your kid.
Can I use it without the app? +
Yes. The system works on paper with jars and envelopes, and did for decades before any app existed. The lessons and workbook are the system; the app just runs it for you if you'd rather not do it by hand.
How is this different from Greenlight, Spriggy, or the storybook thing? +
Kids' debit-card apps (Greenlight, Spriggy, BusyKid, GoHenry) are operational tools — they move real money into real accounts. Story-based apps (Prosperous Kids, My Little Wealth Builder) talk to your kid through characters and Roblox. Lil Banks talks to you — the parent — and gives you the system to install. Different job entirely.
My kid is 10 and I've done nothing yet — am I too late? +
No. Ten is late for the easiest window, but the whole system works 3–18. The difference between starting at 4 and starting at 10 is mostly that the 10-year-old has more existing habits to overwrite. Start anyway.
What if it doesn't stick? +
30-day refund on every paid tier, no questions. And Our Money Rules is free forever — start with that, see if the system feels like your family, upgrade later if it does.
The reason we bother
Your kid is going to look back at this, in twenty years, as the thing that gave them an unfair head start.
The system starts Saturday. Get the free Our Money Rules template. That's it. That's the first move.
Start free →